
BMF Circular on the Research Allowance 2026: Key Changes Explained
A new BMF circular on the research allowance has applied since 27 October 2026. It replaces the 2023 version, covers every open case and rewrites the rules on time records, depreciation and the overhead flat rate. The key changes, each with its paragraph number.

Summary
- The BMF circular of 27 October 2026 replaces the version of 7 February 2023 and applies to all open cases, including earlier years whose allowance has not yet been finally assessed.
- Time records get stricter: a record for every working day, the burden of proof lies with the claimant, and estimating or applying flat rates to wage costs is not permitted (paras. 123, 128). Staff who demonstrably work only on eligible projects and only on R&D need just the minimum details (para. 115).
- The circular now interprets the 2024 and 2025 amendments: depreciation of movable assets, the 20% overhead flat rate for projects started from 2026, and assessment-basis caps of EUR 10 million and EUR 12 million.
- Own work by sole proprietors counts at EUR 40, 70 or 100 an hour, depending on when the hour was worked, and the same amounts cap partners' remuneration for R&D work. For contract research, the date of the order decides between 60% and 70%.
- New in the procedure: the tax office can ask the BSFZ to review a certificate (para. 238a), advance tax payments can be reduced on application (para. 265a), de minimis aid has been published in an EU register since 2026, and new BSFZ certificates cover at most three future financial years (para. 236).
On 27 October 2026, Germany's Federal Ministry of Finance (BMF) issued a revised version of its guidance on the research allowance (Forschungszulage). The new BMF circular on the research allowance replaces the version of 7 February 2023, applies to every open case and spends 114 pages catching up with what the legislator has changed since 2024. If you are claiming the allowance, or already have, one point matters more than the rest. Tax offices now work to a single standard, and in several places a stricter one, most visibly on time records.
The ministry has set every change in bold in the circular itself. This article groups the passages that matter most for a claim by topic and gives the paragraph number (Rn., Randnummer) for each, so you can check any statement against the original.
What the BMF circular is
The Research Allowance Act (FZulG) sets out the tax incentive for research in only a few pages. How tax offices apply it is laid down in the BMF circular, an administrative instruction from the Federal Ministry of Finance agreed with the supreme tax authorities of the federal states. It specifies which wage components count, how hours have to be documented, how contract research and depreciation are treated and how the procedure runs between the certification body and the tax office.
Legally, though, the circular binds only the tax administration, not you and not the tax courts. In practice it is still the yardstick your tax office uses to assess the research allowance, and anyone who disagrees with it will usually have to make the case in an objection or in court. That is reason enough to know the new version before your next claim goes in.
When the new circular applies
The circular is dated 27 October 2026 and carries the reference IV C 3 - S 2020/00059/018/001. It sets no transition period: according to its application rule it replaces the BMF circular of 7 February 2023 (BStBl I p. 364) and is to be applied "in all open cases". It therefore applies immediately, including to financial years before 2026, as long as the allowance for them has not been finally assessed. Publication in the Federal Tax Gazette (BStBl) Part I has been announced, but it is not a precondition for the circular to apply.
What this means for you is that a claim for 2024 or 2025 that is still with the tax office will now be checked against the new rules, including the stricter requirements for time records. The cut-off dates in the statute still apply. Each paragraph says which rule covers which period, and the table in the section on caps sums it up.
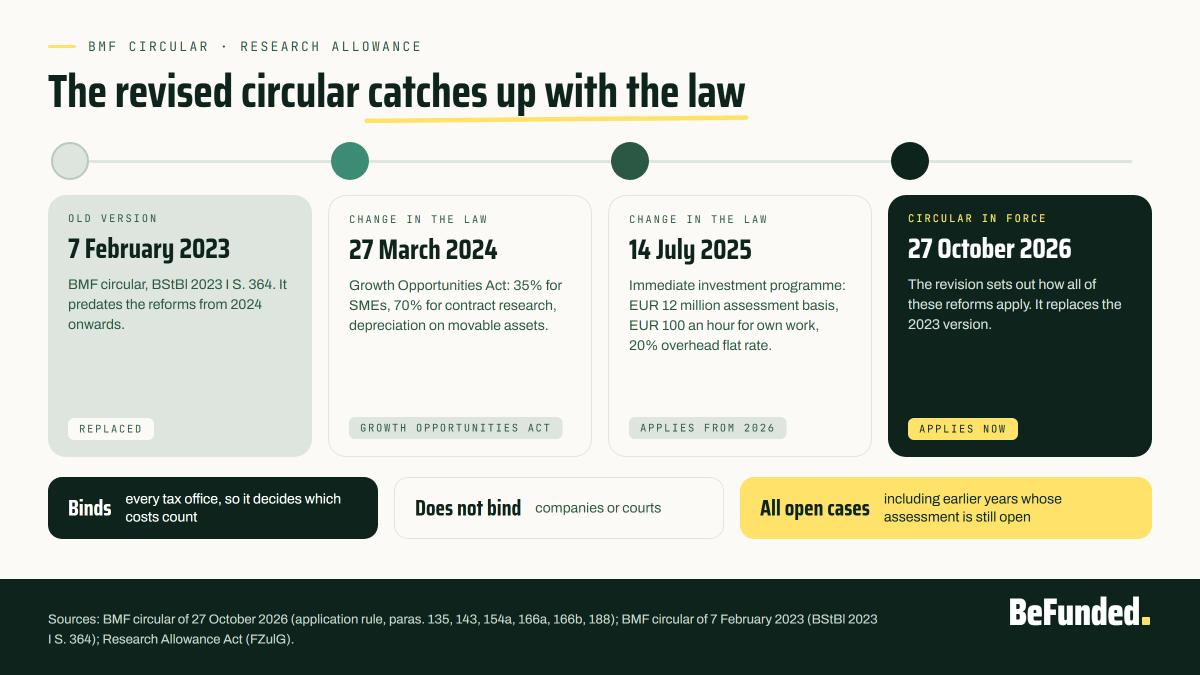
In substance, the revision mostly catches up with the statute. It works in the Growth Opportunities Act (Wachstumschancengesetz) of 27 March 2024, the Act on an Immediate Tax Investment Programme of 14 July 2025 and, for the de minimis register, the Tax Amendment Act 2025. Until now, the effect of these laws could only be read in the FZulG; the circular now also says how tax offices interpret it.
The changes at a glance
Much of the revision is clarification, but some points noticeably change what ends up in your claim. The table lists the most important ones with their paragraph, and the sections below explain each of them.
| Topic | What the new circular says | Paragraph |
|---|---|---|
Time records | record for every working day, burden of proof on the claimant, no estimates or flat rates | paras. 123, 128 |
Staff working only on R&D in eligible projects | minimum details only, no daily record | para. 115 |
Special payments | do not count if clearly paid for work outside the project | para. 90 |
Own work | EUR 40, 70 or 100 an hour, at most 40 hours a week | paras. 131, 135, 138 |
Depreciation | loss in value of movable assets acquired or produced after 27 March 2024 | paras. 141b to 141t |
Contract research | 70% for orders placed after 27 March 2024; agency staff do not count | paras. 142a, 143 |
Overheads | 20% flat rate for projects started after 31 December 2025 | paras. 154a to 154c |
Caps | assessment basis up to EUR 10 million or EUR 12 million, allowance up to EUR 4.2 million for SMEs | paras. 166a, 166b, 190 |
Procedure | tax office can ask for the BSFZ certificate to be reviewed; new certificates cover at most three future financial years | paras. 236, 238a |
Advance payments | reduction on application | paras. 265a to 265e |
De minimis | entry in the EU register from 2026; three-year period counted back from the date of the assessment notice | paras. 310a, 317 to 322 |
Source: BMF circular on the research allowance of 27 October 2026.
Time records: what the tax office now expects
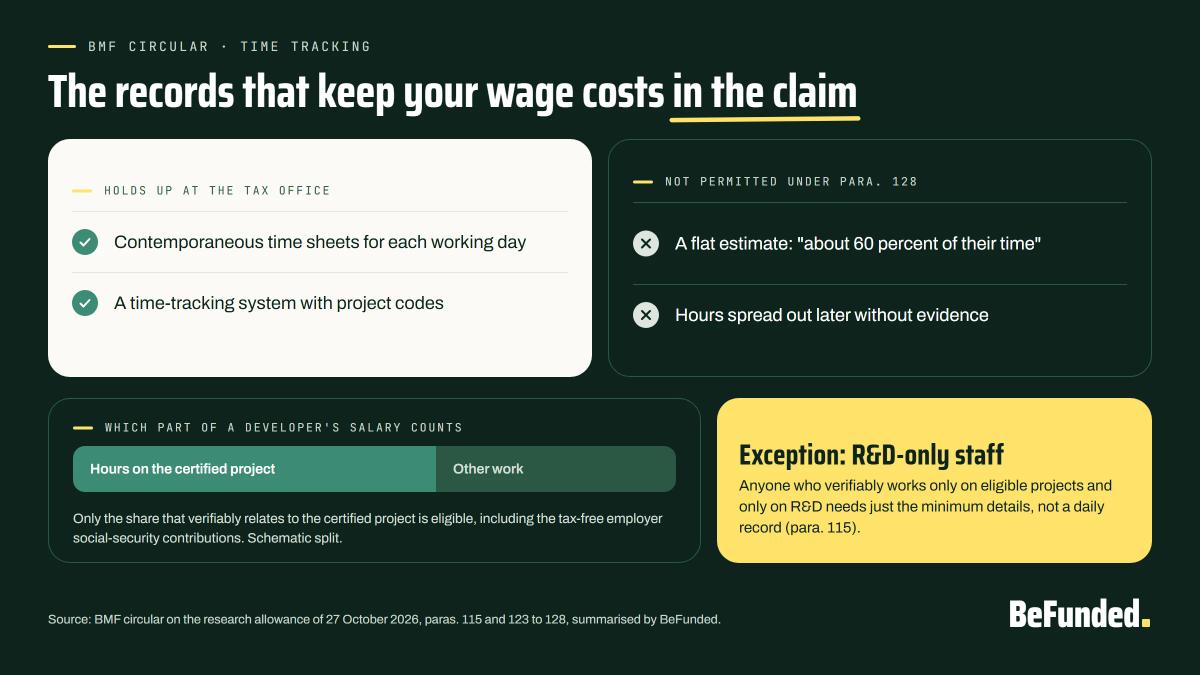
The revision bites hardest on proving wage costs, which is the item the research allowance was built around. It requires a record for every working day on which someone works on the eligible project (para. 123). At a minimum, that record contains the short name of the project, the financial year, the project ID from the BSFZ certificate, the person's name and a short description of their role, such as "lab technician" (para. 124). Start and finish times are not required; what matters is the hours per day and per project.
Paragraph 128 has two new closing sentences, and they are considerably stricter. The burden of proof lies with the claimant, missing or faulty records mean the wage costs are not recognised at all, and the circular states plainly that estimating or applying flat rates to wage costs is not permitted. That fits with rules that applied before. Internal standard hourly rates, departmental average salaries and company-specific averages may not be used (paras. 86, 117); the eligible share is calculated from each person's gross annual salary and contractually agreed annual working time (para. 116).
On the form of the records, by contrast, the circular leaves room. Records kept on paper are countersigned by a project lead at the end of each month, while electronic time tracking needs no such confirmation (para. 125). The GoBD bookkeeping principles apply as amended on 14 July 2025 (para. 127), and the BMF provides an optional template time sheet (para. 126).
A new sentence in para. 115 brings genuine relief. Employees who demonstrably work only on eligible projects and only on R&D no longer need daily records, just the minimum details from para. 124. That suits pure research teams; as soon as the same person also handles support, sales or routine work, the full requirement applies again.
In practice, BSFZ certification rarely fails over time records, whereas the assessment by the tax office does so far more often. The circular says nothing specific about reconstructing hours after the event. Spreading hours across projects from memory in December, however, is an estimate, and para. 128 rules that out. Time tracking therefore starts on the first day of the project.
Wage costs: what counts and what does not
The basic rule is unchanged. Eligible costs are the taxable wages of employees who carry out research on the eligible project, plus the employer's statutory social security contributions under section 3 no. 62 EStG, in the proportion attributable to the project. Special payments such as annual bonuses, performance supplements and overtime pay are part of this.
Paragraph 90 adds a new limit, however: special payments that are clearly made for work outside the project do not increase eligible annual wages. A sales bonus paid to an engineer who also looks after customers stays out of the calculation, while her annual bonus for the project work stays in.
For shareholder-managing directors of a GmbH, the familiar position holds. Their salary counts only if there is an employment relationship recognised for tax purposes with arm's-length pay, and any part treated as a hidden profit distribution is not wages (para. 98). Without such an employment relationship, their work cannot be claimed as own work either (para. 99).
Own work: EUR 40, 70 or 100 an hour
Sole proprietors who carry out research themselves claim a fixed amount for each documented hour of their own work. The amount depends on when the hour was worked: EUR 40 before 28 March 2024, EUR 70 up to the end of 2025 and EUR 100 from 1 January 2026 (para. 135). The cap is 40 hours a week across all eligible projects combined, and for simplicity the calculation may be done monthly, with at most one twelfth of 2,080 hours (paras. 131, 132).
For partners in a partnership, the same scale caps the remuneration for their R&D work (para. 138). The agreement has to be valid under civil law, seriously intended and actually carried out (para. 136), and it must clearly separate pay for the R&D work from pay for other work done for the partnership (para. 137). If your partnership agreement sets one lump sum for "everything", it is worth reviewing before the next claim.
Depreciation: movable assets now count
Since the Growth Opportunities Act, the loss in value of equipment and machinery can also enter the assessment basis. The old circular did not cover this; the new one deals with it in detail in paras. 141b to 141t. An eligible asset is a depreciable movable asset in fixed assets that was acquired or produced after 27 March 2024, is necessary for the project and is used exclusively within the company (para. 141e). In addition, the project in which it is used must have started after 27 March 2024 (para. 141d), and the depreciation can only be claimed for financial years beginning after 31 December 2023 (para. 141c). Exclusive use within the company does not mean use in the project alone: if the asset is also used for other business purposes, only the share of depreciation attributable to its use in eligible projects counts (paras. 141i, 141n).
In practice, two further details decide the amount. First, the BSFZ determines whether the asset is necessary for the project, and the tax office is bound by that finding (paras. 141j, 233), so equipment belongs in the application for certification from the start. Second, low-value assets and assets in a collective item are excluded (para. 141k), while special depreciation and increased deductions are included (para. 141m). Buildings, land and intangible assets are generally not eligible (para. 141f).
Contract research: 60% or 70%
If you commission research from a third party, you can claim part of the fee, and the date of the order is what matters. For projects commissioned after 27 March 2024, 70% counts; for earlier orders, 60% (para. 143). The 70% rate also applies only in financial years that began after 31 December 2023 and only to costs incurred after 27 March 2024. What counts as the start is the specific order for the certified project; a framework agreement on its own is not enough (para. 71).
Paragraph 142a adds a new clarification. Staff borrowed from a staffing or engineering agency who work in your own R&D department are not contract research, because the agency does not carry out the project itself. Only the fee itself is eligible, without deductible VAT and without other costs around the order (paras. 146, 147). Which contractors qualify in the first place is covered in our article on the research allowance for contract research.
Overhead flat rate, funding rate and caps
For projects that started after 31 December 2025, overheads and other operating costs are added as a flat rate: 20% of the other eligible costs of the financial year, with no proof required (paras. 154a, 154b). These costs cannot be claimed individually instead, and only costs from projects that started after that date go into the calculation (para. 154c). A project that started in November 2025 therefore does not receive the flat rate in 2026 either.
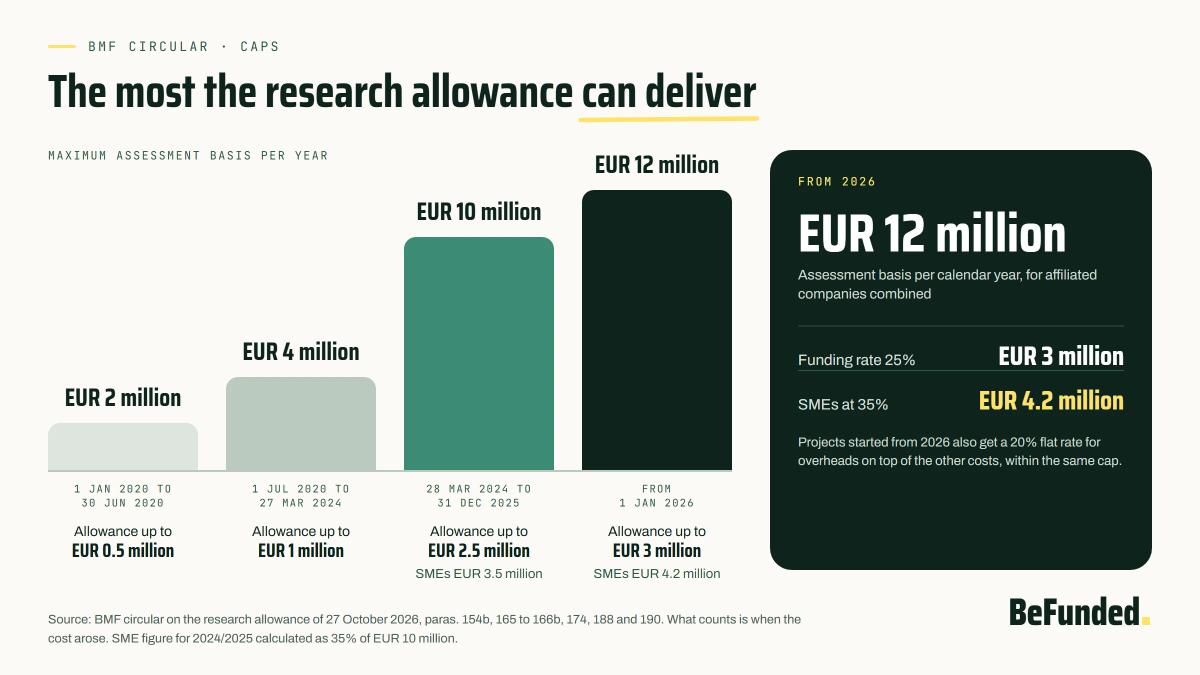
At the same time, the caps have gone up. The assessment basis is capped at EUR 10 million for costs incurred after 27 March 2024 and at EUR 12 million for costs incurred from 1 January 2026 (paras. 166a, 166b). Both caps apply per calendar year to all affiliated companies together (para. 174). The allowance is 25%; SMEs as defined by the EU can apply for ten percentage points more on costs incurred after 27 March 2024, which makes 35% (paras. 188, 291a). That puts the maximum allowance at EUR 3 million per financial year, or EUR 4.2 million for SMEs (para. 190).
| up to 27 Mar 2024 | 28 Mar 2024 to 31 Dec 2025 | from 1 Jan 2026 | |
|---|---|---|---|
Maximum assessment basis | EUR 4 million (EUR 2 million up to 30 Jun 2020) | EUR 10 million | EUR 12 million |
Funding rate | 25% | 25%, SMEs 35% | 25%, SMEs 35% |
Own work per hour | EUR 40 | EUR 70 | EUR 100 |
Contract research | 60% | 70% | 70% |
Depreciation | not eligible | assets acquired or produced after 27 Mar 2024 | as before |
Overhead flat rate | none | none | 20% for projects started from 1 Jan 2026 |
For the assessment basis, funding rate and own work, what matters is when the cost or hour arose; for contract research, the date of the order; for the flat rate, the start of the project. Source: BMF circular of 27 October 2026, paras. 135, 141c to 141e, 143, 154c, 165 to 166b and 188.
Procedure: what changes between the BSFZ and the tax office
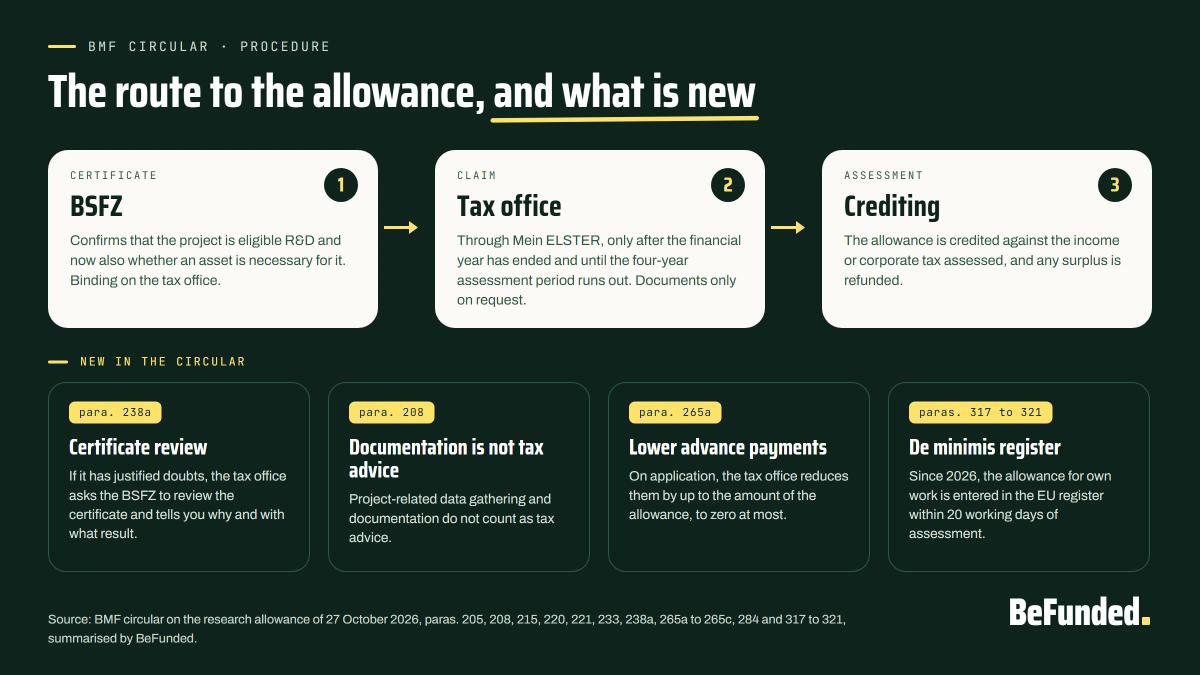
The two-stage route itself stays the same. First the BSFZ, the research allowance certification body, confirms that a project is eligible R&D, and this certificate binds the tax office as a basis decision, now explicitly also as to whether an asset is necessary (para. 233). Then, once the financial year has ended, you file the claim for the research allowance through Mein ELSTER, the tax administration's online portal; a claim filed earlier is invalid (paras. 205, 220). There is no separate deadline, and a claim can be filed until the four-year limitation period for assessment runs out (para. 221). Supporting documents are not attached; you keep them ready until the tax office asks for them (paras. 215 to 218). For entitlements that arose in 2020 or 2021, the new para. 221a adds a relief rule. A claim filed after the regular limitation period still counts as filed in time if the BSFZ received a valid application for certification of the same project before that period ended (31 December 2024 for 2020, 31 December 2025 for 2021) and the claim follows within two years of the tax office learning that the certificate was issued. In that case, proof of when the BSFZ received the application has to be attached to the claim.
What is new is a feedback loop between the two authorities. If the tax office has justified doubts about eligibility, it can ask the BSFZ to review specific points of the certificate. Both authorities may exchange the relevant data for this, and the tax office has to tell you why the review was started and what it found (para. 238a). Your project description and your cost records should therefore describe the same project, in the same terms and with the same people. The validity of a certificate is also newly limited. If you apply before or during the project, the BSFZ has since 18 April 2024 issued it only for past financial years, the current one and at most three full future financial years; if the project runs longer, a new certificate is needed (para. 236). Certificates issued up to 17 April 2024 remain valid without a time limit. For cooperation projects, each partner also needs a certificate of its own that covers its contribution to the project (para. 60).
Another new element is the reduction of advance tax payments. It applies once the allowance has been assessed but the next tax return has not yet been filed. On application, the tax office then reduces the advance payments for the oldest year not yet assessed, provided they can still be adjusted, by up to the amount of the allowance, to zero at most (paras. 265a to 265c). That way the allowance shows up in your cash flow sooner than if it were only credited at the next assessment. How the crediting works in detail is explained in our article on the research allowance payout.
Finally, there is a clarification about advice. Anyone who files the claim with the tax office on a company's behalf, or advises it on the claim, needs to be authorised to provide tax advice, as a tax adviser is. The company can of course file its own claim. New in para. 208 is the statement that project-related financial and technical data gathering and documentation do not count as tax advice. Preparing the figures and the evidence is therefore expressly something different from filing the claim. Costs incurred in connection with the allowance, such as tax adviser fees, are generally deductible as business expenses (para. 285a).
State aid: SME status, de minimis and undertakings in difficulty
The research allowance is state aid under the General Block Exemption Regulation (GBER, in German AGVO), and that has consequences the circular sets out in its fourth part. An undertaking in difficulty as defined by EU state aid law is generally not entitled to the allowance (paras. 2a, 292). The higher 35% rate is only available to SMEs under Annex I of the GBER, and the revision adds a section of its own on this (paras. 291a ff.). How to work out the status is covered in our article on the SME definition.
Own work by sole proprietors is treated differently. The allowance for it does not fall under the GBER and is granted only within the limits of the De Minimis Regulation (paras. 194, 195). The same applies to remuneration for partners if the financial year ends before 28 March 2024. De minimis aid is capped at EUR 300,000 over three years (para. 196), counting the three years before the date of the allowance assessment notice (para. 310a). Since 1 January 2026 it has also been published in a central EU register, within 20 working days of the allowance being assessed and for the first time for claims arising after 24 December 2025 (paras. 317, 320, 321). Our article on de minimis and the research allowance goes into more detail.
What to do now
Because the revision applies immediately and to all open years, a quick check is worthwhile before your next claim goes in or the tax office asks for documents:
- Check your time records against paras. 123 to 128: daily, with the project ID and role, and without hours spread out after the event.
- Identify who in your team works only on R&D and only on eligible projects, since the minimum details are enough for them (para. 115).
- List the equipment a project needs in the application to the BSFZ, so that its necessity is certified (para. 141j).
- Record the start date of every project: the flat rate requires a start after 31 December 2025, depreciation a start after 27 March 2024.
- After the assessment, apply to reduce your advance tax payments if the next tax return is still outstanding and the advance payments can still be adjusted (para. 265a).
Conclusion
The new BMF circular on the research allowance brings less new funding than new clarity. What the legislator added in 2024 and 2025, namely depreciation, the overhead flat rate, higher rates and higher caps, is now interpreted the same way by every tax office. In return, the circular tightens the documentation requirements, and because it applies to all open cases, that also affects years already sitting with the tax office.
We prepare the project description for the BSFZ and everything for the tax-office claim, ready for you or your tax adviser to file, and check your time records against para. 128: success-based and end to end. A free initial check shows what is realistic in your case.
Sources: BMF circular on the research allowance of 27 October 2026 (in German), reference IV C 3 - S 2020/00059/018/001; Research Allowance Act (FZulG) (in German). As of 9 November 2026.
FAQ
It is guidance from the Federal Ministry of Finance that obliges tax offices across Germany to interpret the Research Allowance Act in the same way. It covers the details the statute only touches on: wage costs and time records, own work, depreciation, contract research, caps and the procedure. A revised version has applied since 27 October 2026, replacing the circular of 7 February 2023.
It binds tax offices directly, not companies and not the tax courts. In practice there is no way around it, because your tax office checks your claim against exactly these rules. If you take a different view, you will usually have to argue it in an objection or in court.
Hours per person have to be recorded for every working day on the project, with the project, financial year, BSFZ project ID, name and role (paras. 123, 124). Start and finish times are not needed. The burden of proof lies with the claimant, and estimates or flat rates are not permitted (para. 128). Staff who demonstrably work only on eligible projects and only on R&D need just the minimum details (para. 115).
No. The BSFZ applies its own criteria to decide whether a project is technically eligible R&D, and it now also certifies whether an asset is necessary for it. The BMF circular governs the assessment by the tax office, in other words the cost side. What is new is that the tax office can ask the BSFZ to review a certificate if it has justified doubts (para. 238a).
Since its date, 27 October 2026. According to its application rule it applies to all open cases, including earlier financial years whose allowance has not yet been finally assessed. The cut-off dates in the statute, for example for caps and hourly rates, continue to apply.
Only to projects that started after 31 December 2025. For those, a flat 20% of the other eligible costs is added, with no proof required (paras. 154a to 154c). A project that started in 2025 or earlier does not receive the flat rate in later years either.
Yes, provided the allowance has been assessed, you have not yet filed the next tax return and the advance payments can still be adjusted. The tax office will then, on application, reduce the advance payments for the oldest year not yet assessed by up to the amount of the allowance, to zero at most (paras. 265a to 265c).

Related Posts

Manufacturing R&D Tax Credit in Germany: What the Forschungszulage Pays Manufacturers in 2026
The manufacturing R&D tax credit in Germany is the Forschungszulage, a tax-based allowance that pays 25% of eligible R&D costs, or 35% for small and medium-sized enterprises (SMEs). Any company taxable in Germany can claim it for a project that is new, technically uncertain and planned.
 Aydan Aliyeva 20 November 2026 · 13 min read

Grant Consultant: What They Do and How Success Fees Work in Germany & the EU
A grant consultant is an outside adviser who matches your project to a funding programme, writes and assembles the application, and often handles the reporting once the money arrives. Many grant consultants tie part of their fee to the result through a success fee.
 Kirill Rubinstein 17 November 2026 · 12 min read

Biotech Funding in Europe: Grants and Tax Incentives for 2026 and 2027
Biotech funding in Europe beyond VC: which grants and tax incentives German biotech startups and SMEs can use in 2026, and how far each one reaches.
Kirill Rubinstein 12 November 2026 · 14 min read