KfW innovation loan consulting: your financing, done for you.
KfW's innovation and digitalisation loans finance R&D, new products and digital transformation at favourable, promotional terms. We structure the case and run it through your house bank.
Promotional finance for innovation
The KfW innovation and digitalisation loans (ERP-Förderkredit Innovation 513/514 and Digitalisierung 511/512, until June 2025 the ERP-Digitalisierungs- und Innovationskredit) provide low-interest financing for R&D, market introduction and digital transformation, optionally with 50% of the risk taken by KfW.
Unlike a grant, this is finance: favourable rates, long terms and optional 50% risk cover for your house bank. It runs on the Hausbank principle. See who qualifies further down. Terms and the application route are explained in the KfW innovation loan guide.
It's finance, not a grant, but on terms a bank can't match
A KfW innovation loan is repaid, but at subsidised interest, with long maturities and, crucially, risk relief that makes your house bank comfortable saying yes.

Subsidised rates set by your risk and collateral class, well below a standard commercial loan.
Up to €7.5m at the Basis stage and €25m at LevelUp and HighEnd: enough to fund a whole innovation or digitalisation project.
Optionally, KfW takes 50% of the credit risk (programmes 514 and 512, from two sets of annual accounts), lifting much of the risk off your house bank, often the difference between yes and no.
KfW lends through your bank (Hausbankprinzip). We prepare the case and coordinate both sides.
The two products we use most
The right KfW programme depends on whether your project clears the innovation/digitalisation criteria, and on your company's age and size. We match it.
ERP-Förderkredit Innovation (513/514)
For R&D, new products and processes and their implementation, up to €25m per project, optionally with 50% risk cover; from the LevelUp stage there is a 3 or 5% grant supplement (at most €200,000). Successor to the ERP-Digitalisierungs- und Innovationskredit (380).
ERP-Förderkredit Digitalisierung (511/512)
For hardware and cloud migration (Basis, with the KfW digitalisation check), digital transformation and IT security (LevelUp) through to AI in value creation (HighEnd), optionally with 50% risk cover (512).
Indicative programme features. Exact volumes, terms, interest and liability-exemption levels follow the current KfW programme conditions, we confirm them with you and your house bank. kfw.de
The terms at a glance
A KfW loan is repaid, but on terms a commercial bank rarely matches. The figures are programme-specific; these are the headline terms of the ERP-Förderkredit Innovation (KfW information sheet 513, as of 23 April 2026).
up to €25m
loan amount
Up to €7.5m at the Basis stage, up to €25m at LevelUp and HighEnd; there is no minimum amount.
up to 100%
financing
Of eligible costs, with full disbursement and no up-front deduction.
up to 10 yrs
maturity
With at most two grace years and an interest rate fixed for the whole term.
optional 50%
liability release
In programmes 514 (innovation) and 512 (digitalisation), KfW takes half of your bank's credit risk on request; at least two sets of annual accounts are required.
You apply through your own bank (the Hausbankprinzip), always before you start. The interest rate is set per borrower through KfW's risk-adjusted system, capped under a published maximum for your price class.
Who it's for, and the house-bank route
KfW does not lend to you directly. You apply through your own bank, always before the project starts. The full KfW innovation loan requirements are in the guide.
SMEs and larger Mittelstand firms with up to €500m group turnover can apply for the KfW innovation loan.
Dedicated start-up programmes such as the ERP-Gründerkredit StartGeld for companies under five years old.
You apply through your own bank, which forwards the application to KfW, and always before you sign or start.
In the innovation and digitalisation loans (514 and 512), KfW optionally takes 50% of the bank's default risk, so a bank lends even to thin-collateral firms.
Why there's no single headline rate
KfW uses a risk-adjusted interest system, so your rate is set for your case, under a published ceiling.
Your bank maps your creditworthiness and collateral to a KfW price class, each with a capped maximum rate.
The rate is below the open market and capped under the published maximum, with full disbursement and no up-front deduction.
It is a loan, repaid, but with long maturities, grace years and liability release a commercial bank rarely matches.
What a KfW innovation loan funds
Promotional credit is flexible: it can finance the whole project, not just the hardware.
Machinery, equipment, buildings and other fixed assets for the new product, line or site.
The operating resources an innovation or growth project ties up, financed alongside the investment.
Development costs, software, and platform or digitalisation projects, where the innovation programmes apply.
The loan can cover the full eligible cost and is disbursed in full, with no up-front deduction.
See if your project fits a KfW innovation loan
Tell us about your project. A funding advisor reviews your case by hand, then either comes back with feedback or a few follow-up questions. No obligation.
- Whether a KfW loan is the right fit
- A first read on the funding amount
- What to prepare before you apply
From first call to funding
Four steps. You stay focused on the work; we handle the funding end to end, on a fee agreed in advance.
Funding-tier check
We assign your project to the ERP-Förderkredit Innovation (513/514) or Digitalisierung (511/512) and to a funding tier. The tier decides the interest rate and whether you get a 0, 3 or 5% grant supplement.
Bank documents
We write the project description and the cost and financing plan and compile the documents your house bank needs for its credit review.
House bank application
Your house bank files the application with KfW, always before the project starts. We align the case with the bank and handle queries through to approval.
Approval and drawdown
After approval you sign the loan agreement and draw down the funds. From the LevelUp tier we make sure you request payment of the grant supplement within three months of the loan being fully disbursed.
KfW in practice
Practical examples based on real projects we have taken through KfW, from first scoping to the funding decision. Anonymised, figures rounded.

How a manufacturer financed a new product line with a low-interest KfW innovation loan - what a KfW…
Read the story
How a company financed the scale-up of an innovative product to series production with a low-interest…
Read the story
How a company financed a digitalisation and platform-rebuild programme with a low-interest KfW loan…
Read the storyIndustries we fund
We've secured German and EU funding across the innovation economy. If you're doing genuine development, your field almost certainly fits.
Why BeFunded exists
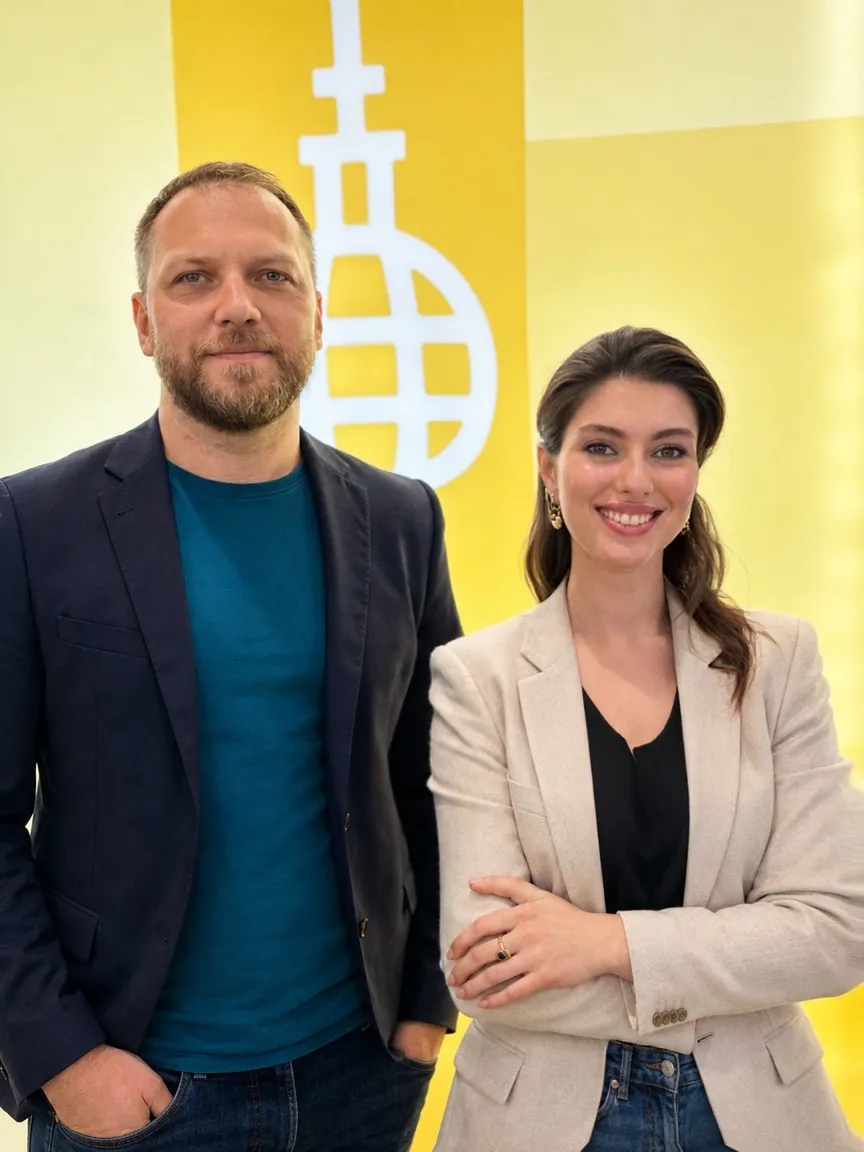
Two founders, one mission: help every innovator in Europe fund what they build.
Our mission
To make public funding genuinely accessible to everyone building something new in Europe. Across research and development, health, agriculture, energy and far beyond, billions are set aside each year to back innovation, yet too much of it never reaches the teams doing the actual work. We want to change that, so that funding lands where it belongs and keeps innovation in Europe moving forward.
From founder to founder: we have been on the client side ourselves, navigating Europe’s funding programmes first-hand, and we learned how much complexity, paperwork and uncertainty stands between a good project and the money meant to support it.
KfW innovation-loan questions, answered
The basics on terms, volume and the house-bank route.
At the LevelUp and HighEnd stages the ERP grant supplement is 3 or 5% of the loan amount paid out, at most €200,000; at the Basis stage there is none. It is granted as de minimis aid, and you do not pay it back.
Yes. A KfW innovation loan is promotional finance, not a grant: low-interest, sometimes with partial liability relief for your bank, and repaid on far better terms than a standard loan.
The KfW innovation loan goes up to €7.5m at the Basis stage and up to €25m per project at the LevelUp and HighEnd stages; there is no minimum amount. The exact figure depends on your plan and the funding stage.
You apply for a KfW innovation loan through your house bank, the Hausbankprinzip. We prepare the case and coordinate with the bank and KfW.
A KfW innovation loan finances R&D, new products and processes, market introduction and investments in digital transformation, all at promotional low-interest conditions.
For BeFunded's support with KfW innovation loans, our fee is a fixed share plus a success component, both agreed in advance. So you know before the start what the support costs.
Your house bank checks creditworthiness and collateral, files the application with KfW and pays out the loan. We make sure your project lands in the right funding tier and the costs are properly documented. That matters: if a LevelUp-eligible project with a €2m loan ends up in the Basis tier, you miss out on €60,000 of grant supplement.
Yes. The loan and the Research Allowance can sit side by side as long as the same costs are not funded twice and total aid stays within EU limits. The ERP grant supplement from the LevelUp tier runs under the de minimis regulation and counts towards your de minimis budget.
Ask us anything
Tell us about your project and we'll assess your case by hand. No prep, no obligation. Prefer to talk?