
Accounting for the Research Allowance: Books and Tax
The research allowance is credited against your assessed tax, not booked as grant income, and that single mechanism decides every entry that follows. How to recognise the claim, where it sits in the balance sheet and the P&L, and why your R&D costs stay fully deductible.

Summary
- The research allowance is not a classic grant but a tax credit: it is set off against income or corporate tax at the next assessment, and any excess is paid out. That mechanism drives all of the accounting.
- The allowance does not increase taxable profit and does not reduce R&D expenses: personnel costs remain fully deductible, and the allowance runs separately through the tax assessment.
- Under German GAAP a receivable against the tax office arises: usually recognised once the BSFZ certificate is in place and eligible costs have been incurred, at the latest with the assessment notice.
- In the P&L the prevailing view puts the allowance under other operating income; showing it inside the tax line is rejected by the audit guidance, and for loss-making startups the income presentation is the one investors can actually read.
- Agree the concrete entries with your tax advisor or auditor: the FZulG fixes the mechanics, the presentation details depend on legal form and reporting framework.
Why the research allowance is booked differently from a grant
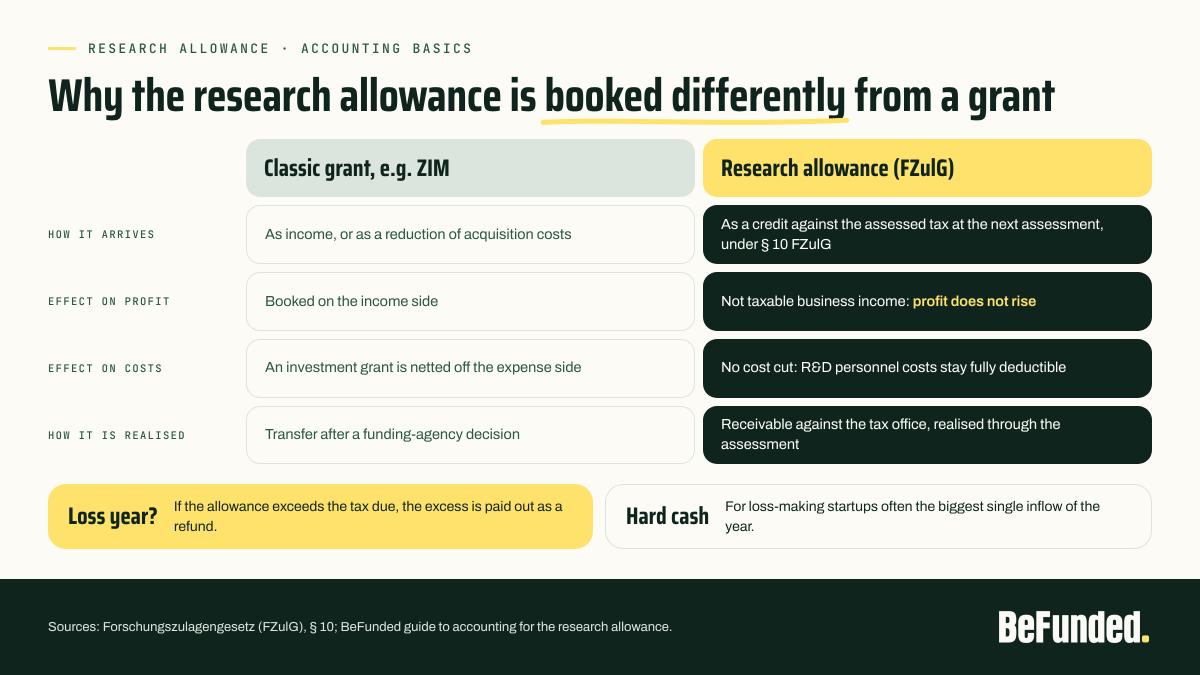
Classic grants such as ZIM arrive as income or reduce acquisition costs. The research allowance works differently: under § 10 FZulG it is credited against the assessed tax at the next assessment. If the allowance exceeds the tax due, typically in loss years, the excess is paid out as a refund.
Three accounting principles follow from that mechanism:
- The allowance is not taxable business income. It does not increase profit.
- It does not cut any expenses: R&D personnel costs remain fully deductible.
- It arises as a receivable against the tax office and is realised through the assessment, not by a transfer following a funding-agency decision.
The lifecycle in the books
Step 1: costs run as usual
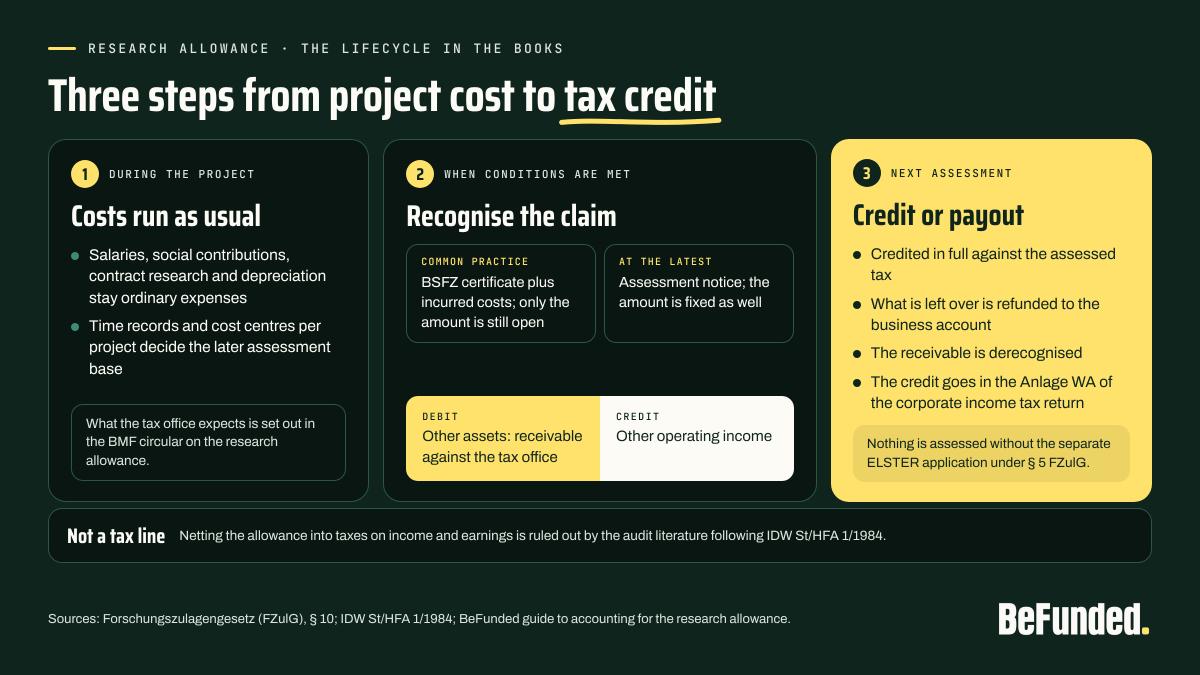
During the project nothing changes: salaries, social contributions, contract research and depreciation are ordinary expenses. What matters is the project-level documentation (time records, cost centres), because it later determines the assessment base. What the tax office expects is set out in the BMF circular on the research allowance.
Step 2: recognising the claim
Once the substantive conditions are met, the claim becomes solid enough for the balance sheet, and practice settles on one of two moments:
- With the BSFZ certificate and incurred costs: many companies recognise the claim as an other asset here, because the certificate is binding confirmation that the work qualifies at all. Only the amount is still open.
- At the latest with the assessment notice: from that point the amount is fixed as well.
The entry is debit other assets (receivable against the tax office), credit other operating income. Netting the allowance into the tax line looks tidy, but the audit literature following IDW St/HFA 1/1984 rules that out: presentation under taxes on income and earnings is not an option. The remaining detail belongs in the conversation with your tax advisor, who knows your reporting framework.
Step 3: credit or payout
At the next assessment the allowance is credited in full against the assessed tax, so the receivable is netted against what you owe. Only what is left over after that comes back as a refund on the business account, and the receivable is derecognised. Where the credit belongs in the corporate income tax return, namely in the Anlage WA (the annex for additional information), is covered in our article on the research allowance in the corporate income tax return; how long the money actually takes is the subject of the piece on the research allowance payout.
Is the research allowance tax-free?
The allowance does not create taxable income. Technically it is a credit against assessed tax rather than a grant on the income side, and the funded R&D costs stay fully deductible on top of that. Nothing is netted off the expense side the way an investment grant would be.
Two points behind that are easy to mix up:
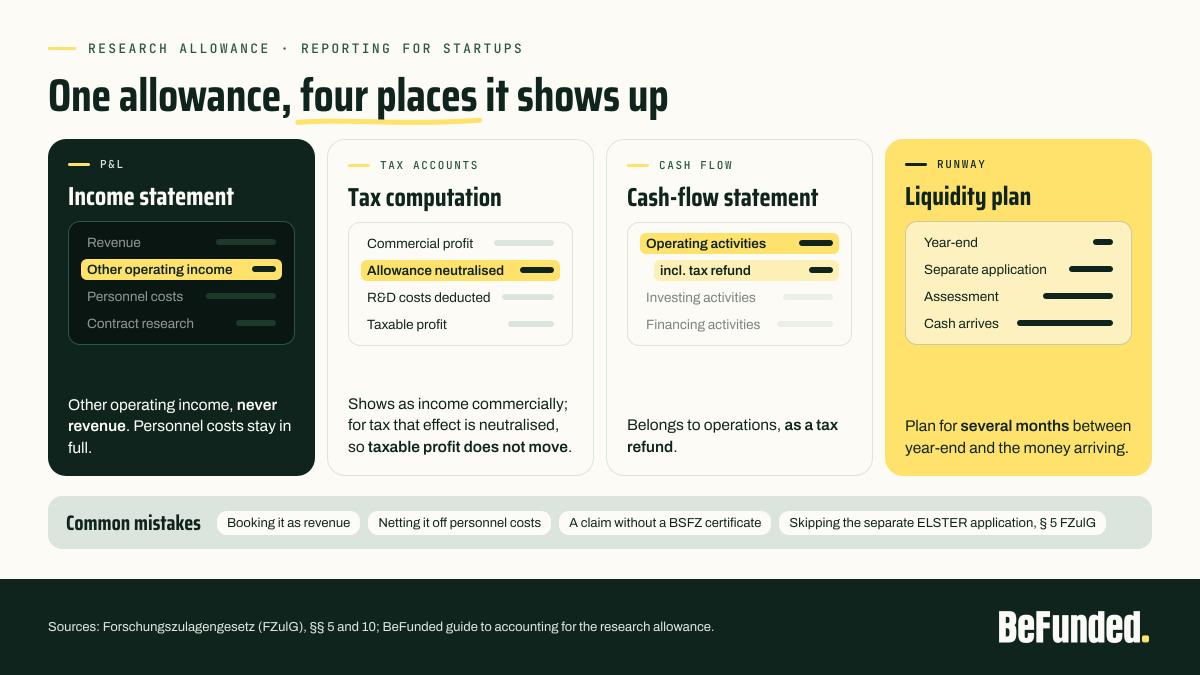
- Commercial versus tax accounts: commercially the allowance shows as income; for tax purposes that effect is neutralised, so taxable profit does not move.
- Sole proprietors with own work: the share of the allowance attributable to own hours counts as de-minimis aid under state-aid law, see our article on de-minimis and undertakings in difficulty. That changes the evidence requirements, not the tax treatment.
Loss-making startups: what to show investors
For startups in the loss phase the research allowance is hard cash, often the biggest single inflow of the year. In reporting and in pitch material it pays to keep it clearly apart:
- In the P&L the allowance appears as other operating income, not as revenue.
- In the cash-flow statement it belongs to operations, as a tax refund.
- For runway planning the assessment date matters: several months realistically pass between year-end and the money arriving.
Common mistakes
- Booking it as revenue or grant income with no separate line: that distorts your KPIs and the tax computation in one go.
- Netting the allowance off personnel costs: wrong, the expenses stay where they are, in full.
- Recognising a claim with nothing behind it: without the BSFZ certificate the balance-sheet position is open to challenge.
- Waiting for the tax return to do the work: the allowance is assessed on a separate application filed through ELSTER, the tax authorities' online portal, under § 5 FZulG, and without that application the tax office assesses nothing, however clean the books are.
Conclusion
Accounting for the research allowance is straightforward once the mechanics are clear: receivable instead of grant, credit instead of transfer, no profit increase, no cost reduction. The finer points of presentation belong with your tax advisor; the foundation, a clean assessment base with solid evidence, is what we build.
We run the whole claim success-based and end to end, from the BSFZ certificate to audit-proof cost documentation your bookkeeping can rely on.
FAQ
The allowance does not increase taxable profit: it is credited against the assessed income or corporate tax, and any excess is refunded. It is not taxable business income, and it does not reduce your deductible R&D costs either.
Under German GAAP the claim is recognised as an other asset (receivable against the tax office), and the credit entry is other operating income. Showing it inside the tax line is the minority view and is rejected by the audit guidance the profession follows. Align the detail with your tax advisor or auditor.
A recognisable claim requires the substantive conditions to be met, in particular a BSFZ certificate and incurred eligible costs. Many companies recognise once the certificate is issued; at the latest, the receivable is certain with the assessment notice.
No. Unlike classic investment grants, the research allowance is not deducted from acquisition or personnel costs. R&D expenses remain fully deductible business expenses; the allowance runs separately through the tax assessment.

Related Posts

Manufacturing R&D Tax Credit in Germany: What the Forschungszulage Pays Manufacturers in 2026
The manufacturing R&D tax credit in Germany is the Forschungszulage, a tax-based allowance that pays 25% of eligible R&D costs, or 35% for small and medium-sized enterprises (SMEs). Any company taxable in Germany can claim it for a project that is new, technically uncertain and planned.
 Aydan Aliyeva 20 November 2026 · 13 min read

Grant Consultant: What They Do and How Success Fees Work in Germany & the EU
A grant consultant is an outside adviser who matches your project to a funding programme, writes and assembles the application, and often handles the reporting once the money arrives. Many grant consultants tie part of their fee to the result through a success fee.
 Kirill Rubinstein 17 November 2026 · 12 min read

Biotech Funding in Europe: Grants and Tax Incentives for 2026 and 2027
Biotech funding in Europe beyond VC: which grants and tax incentives German biotech startups and SMEs can use in 2026, and how far each one reaches.
Kirill Rubinstein 12 November 2026 · 14 min read